
It would be totally fair to accuse me of being “corporate governance” pilled, as most of the investments I’ve made so far this year have had some type of “dark arts” style theme to them. I’m ok with that accusation; I wish I had leaned heavier into the signals as, while there have certainly been a few clunkers, on the whole the play / thesis has worked out pretty well.
I try to look through all dark arts plays (at least all of them that I catch, though I think I’m pretty good at catching most of them!), as I personally think any time a company goes out of their way to give management a special grant, it’s worth tracking… but I will also admit that I think these packages need to be looked at with a very careful / skeptical eye, as it’s really easy for boards to just continuously load up their management teams in a way that will make them fabulously rich if they pay off while ensuring management teams know they will be made whole if the package doesn’t work.
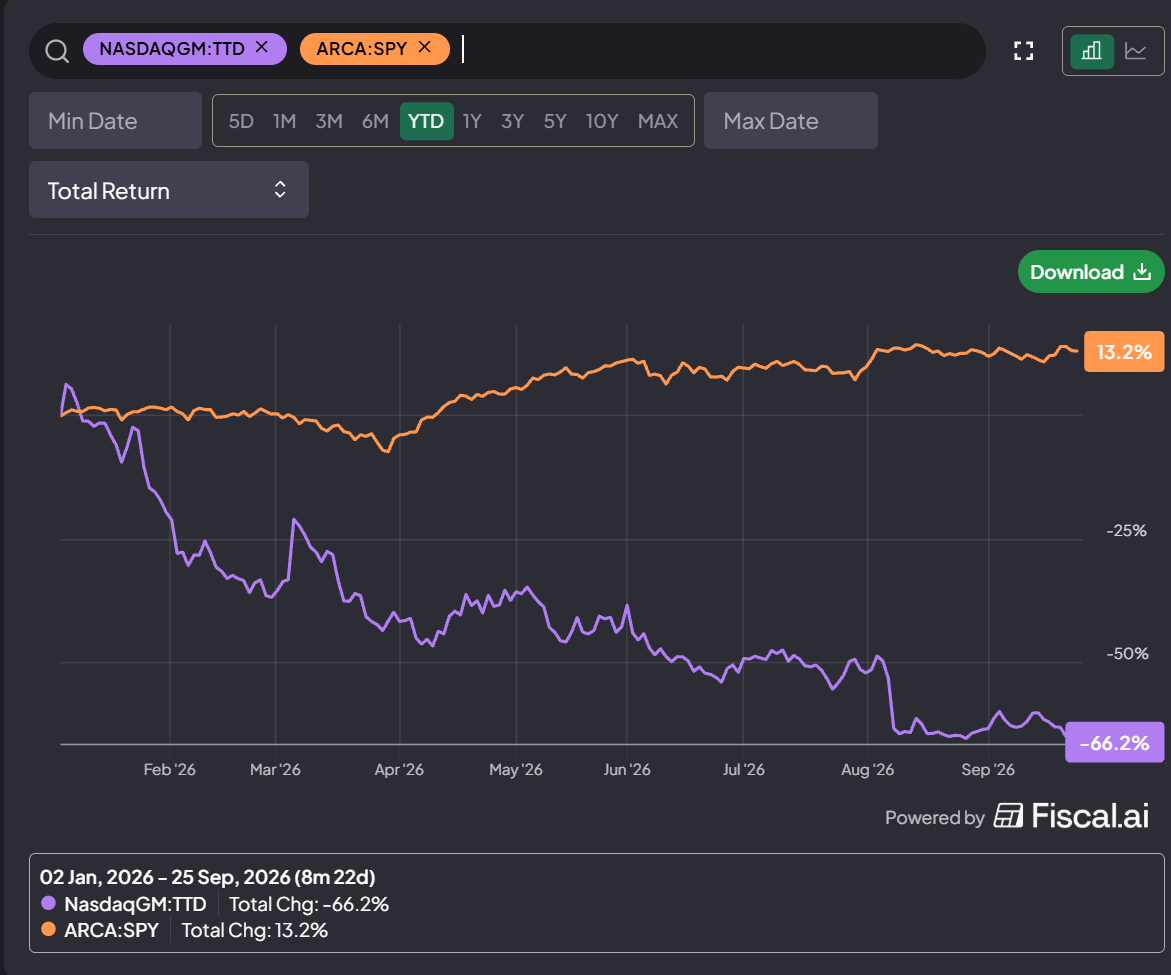
Case in point: TTD’s recent package. This is the package I’ve probably received the most inbounds on over the past few months. Why? Because the bull case writes itself! TTD’s stock has been absolutely blasted this year, driven by a combination of poor financials and SaaS-pocalypse fears.
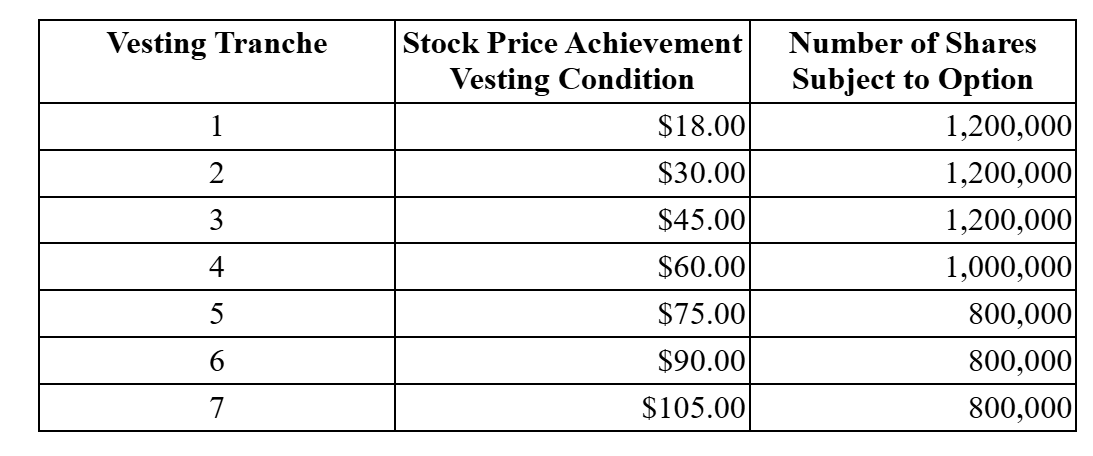
In response, TTD gave their CEO a ten-year options package that calls for the stock to go all the way to $105/share to vest in full. With the stock currently trading in the low double digits, that would be a ~8x in ten years to hit in full. Not bad!
And not only is the CEO loaded up on options…. He made one of the largest insider purchases of all time earlier this year. I wrote up some quick thoughts on that purchase in near real time, so check that writeup for more history. For context, I’ve previously written up insider purchases, and a $150m open market buy is among the largest of all time.
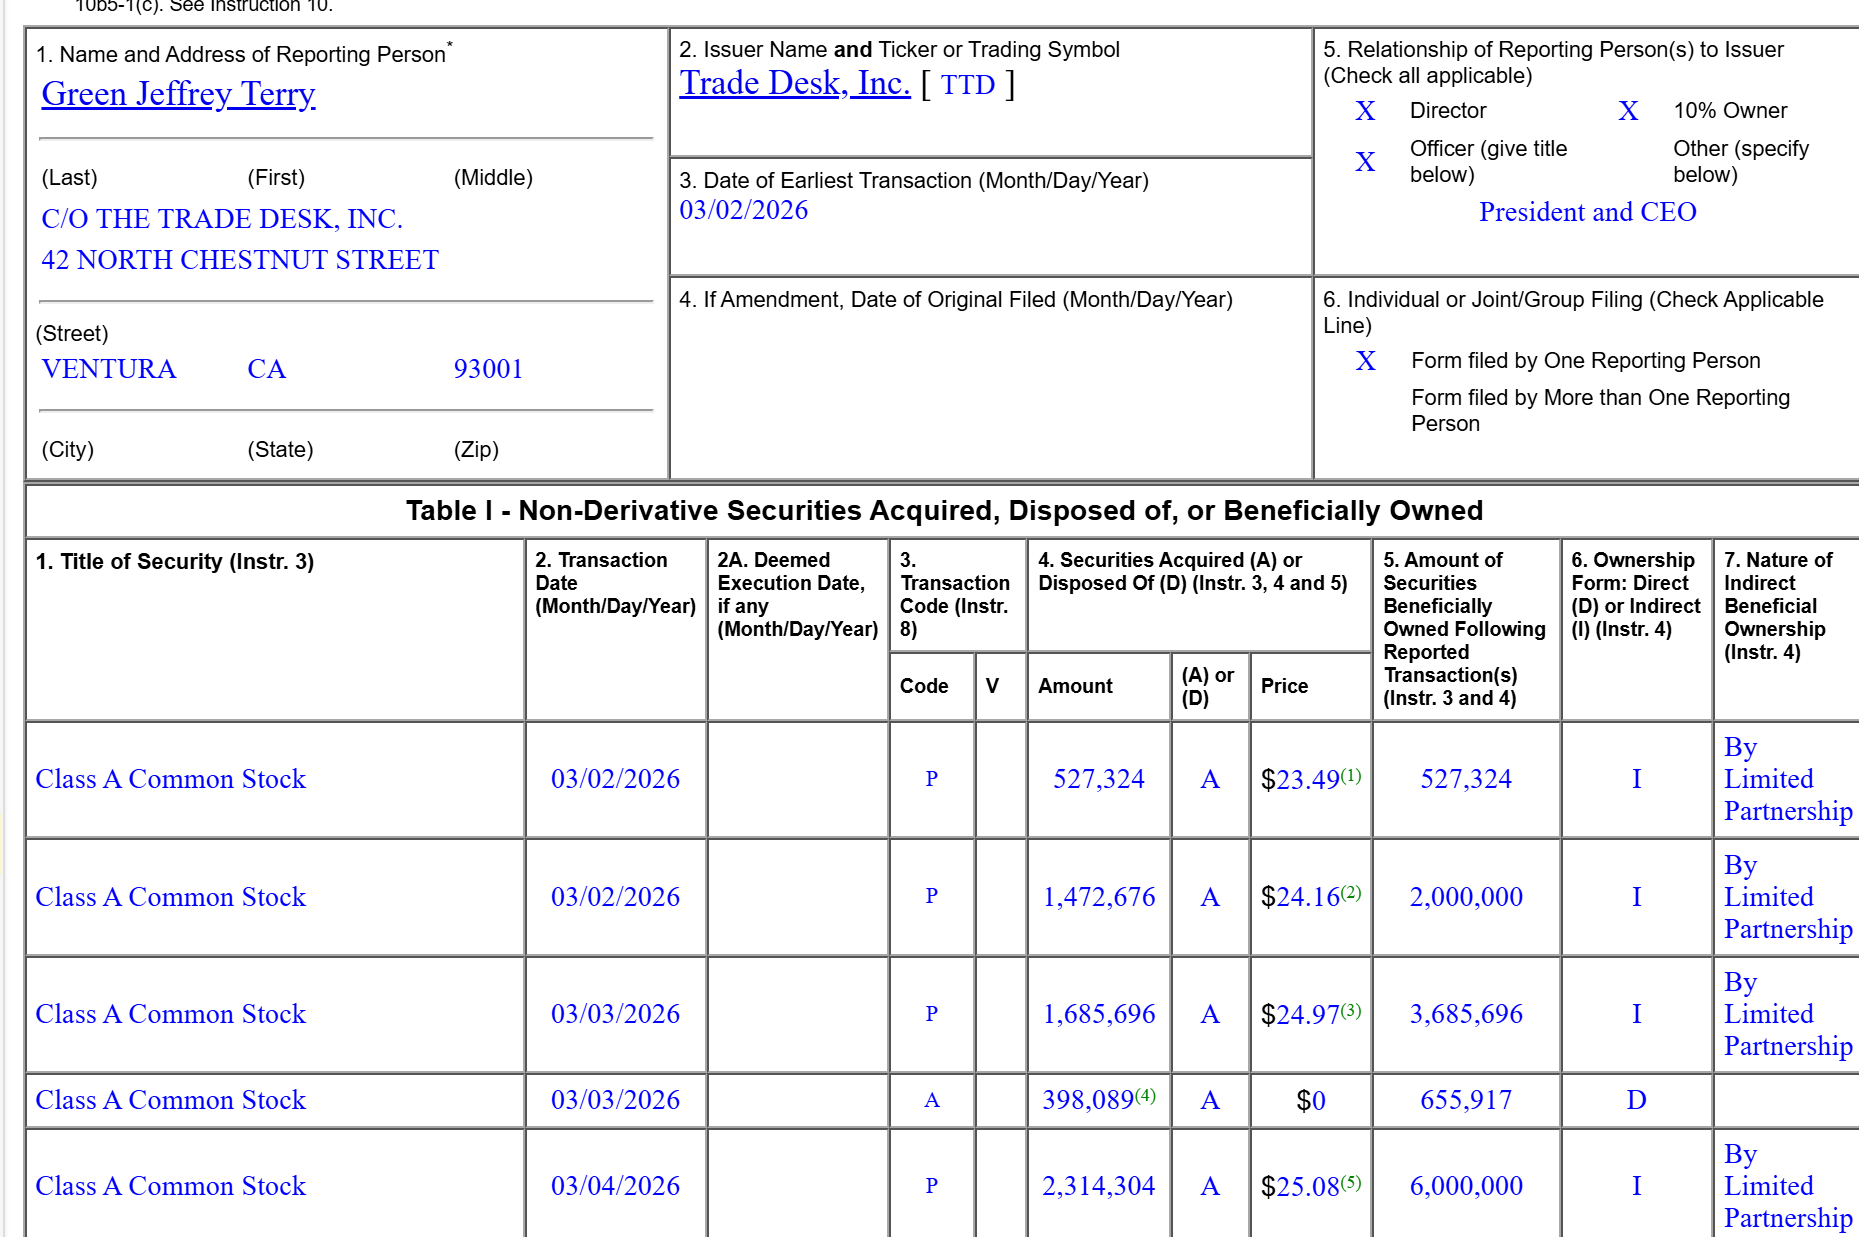
So you’ve got all the makings of a great investment: huge insider alignment, a massive dark arts package that requires the stock to go up a ton to vest in full, a CEO who made an open market purchase at almost twice today’s share price, and a former growth darling that’s been beaten down. Sounds like a value investor’s dream, right?
Perhaps…. but you can probably tell I’m skeptical, and you’re right.
If all of the stars are aligning, why don’t I think there’s a ton of signal in this package?
Well, to start, I’d note that TTD just filed an option repricing proxy. Options repricings are rare but not unheard of; basically, if a company grants a bunch of options at $100 and the stock goes to $10, the company goes to their shareholders and says “we need to price these options down” on the thesis that the massive underwater options create employee retention and alignment problems.
There is (almost) literally nothing I hate more than options repricing.
Why?
Because it creates such a “heads I win; tails I don’t lose” scenario. If the stock had gone up 10x, the employees would have created enormous wealth alongside shareholders. Would they have given some of that back because they were overpaid when the stock worked super well? Of course not! So why should employees get a mulligan when the stock cracks and shareholders suffer?
I’ll also note that TTD’s repricing package is even more egregious than most; I have seen companies go for an options repricing that excludes C-suite executives. The basic theory there is the repricing helps retain rank and file employees, but since the C-suite is paid better (and has more control over the company performance and ultimately the stock price) the C-suite shouldn’t get a do over. For example, that’s what Lions Gate did with their repricing a few years back.
Not TTD! TTD is repricing the C-suite’s options too! That’s a textbook definition of a board making sure the C-suite gets paid no matter how the shareholders do.
The TTD proxy has one other tidbit: it notes that the CEO’s performance options from October 2021 are not eligible for repricing. And that brings me to the second reason I don’t think the current performance package has a ton of signal: The board has given these out before.
In October 2021, TTD’s stock was trading at ~$68.29/share, and the board gave the CEO the following ten-year options vesting package:
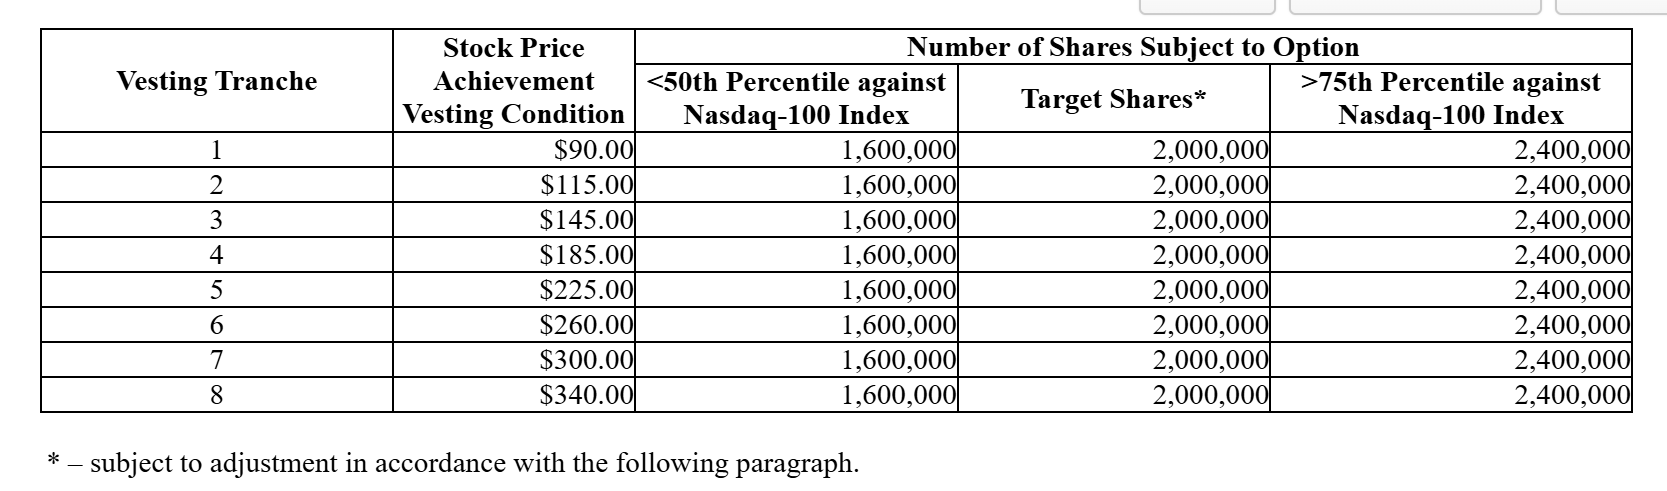
Obviously, that looks a lot like the package that they just gave their CEO…. except the stock price is a whole lot lower today.
There’s nothing wrong with a company giving a CEO a stock price heavy comp package and doing it again a few years later. However, I’d contend that if the company does it repeatedly, it does not carry a ton of signal. It’s a great way to ensure alignment, but the types of “this package could generate alpha” signals that I generally look for happen when a company goes out of their way to give a CEO a stock price heavy package, not when they consistently do it.
I’d also note that, in many ways, the October 2021 package from TTD is superior / more aligned than the current package. It included a stock price modifier based on how the stock performed against the Nasdaq (the current package drops that modifier), and it had the same number of shares vesting in each tranche (the new package has more shares vesting at lower numbers that are easier to hit).
Now, a TTD bull might look at all that and say, “sure, TTD is maybe a little too generous with compensation. But this is a competitive industry with in demand employees who need to be paid well to be retained; it doesn’t change the bullish nature of the performance options package. And remember that the CEO just wrote a ~$150m check to buy stock in the open market!”
Those are fair points, and I thank my strawman TTD bull for bringing up the open market purchase.
Is that open market purchase a bullish signal?
Absolutely!
But if I told you TTD’s CEO had sold >$1B of stock over the past few years, would that change your interpretation of the insider purchase? Does it seem a little less bullish knowing how much he’d cashed out already?
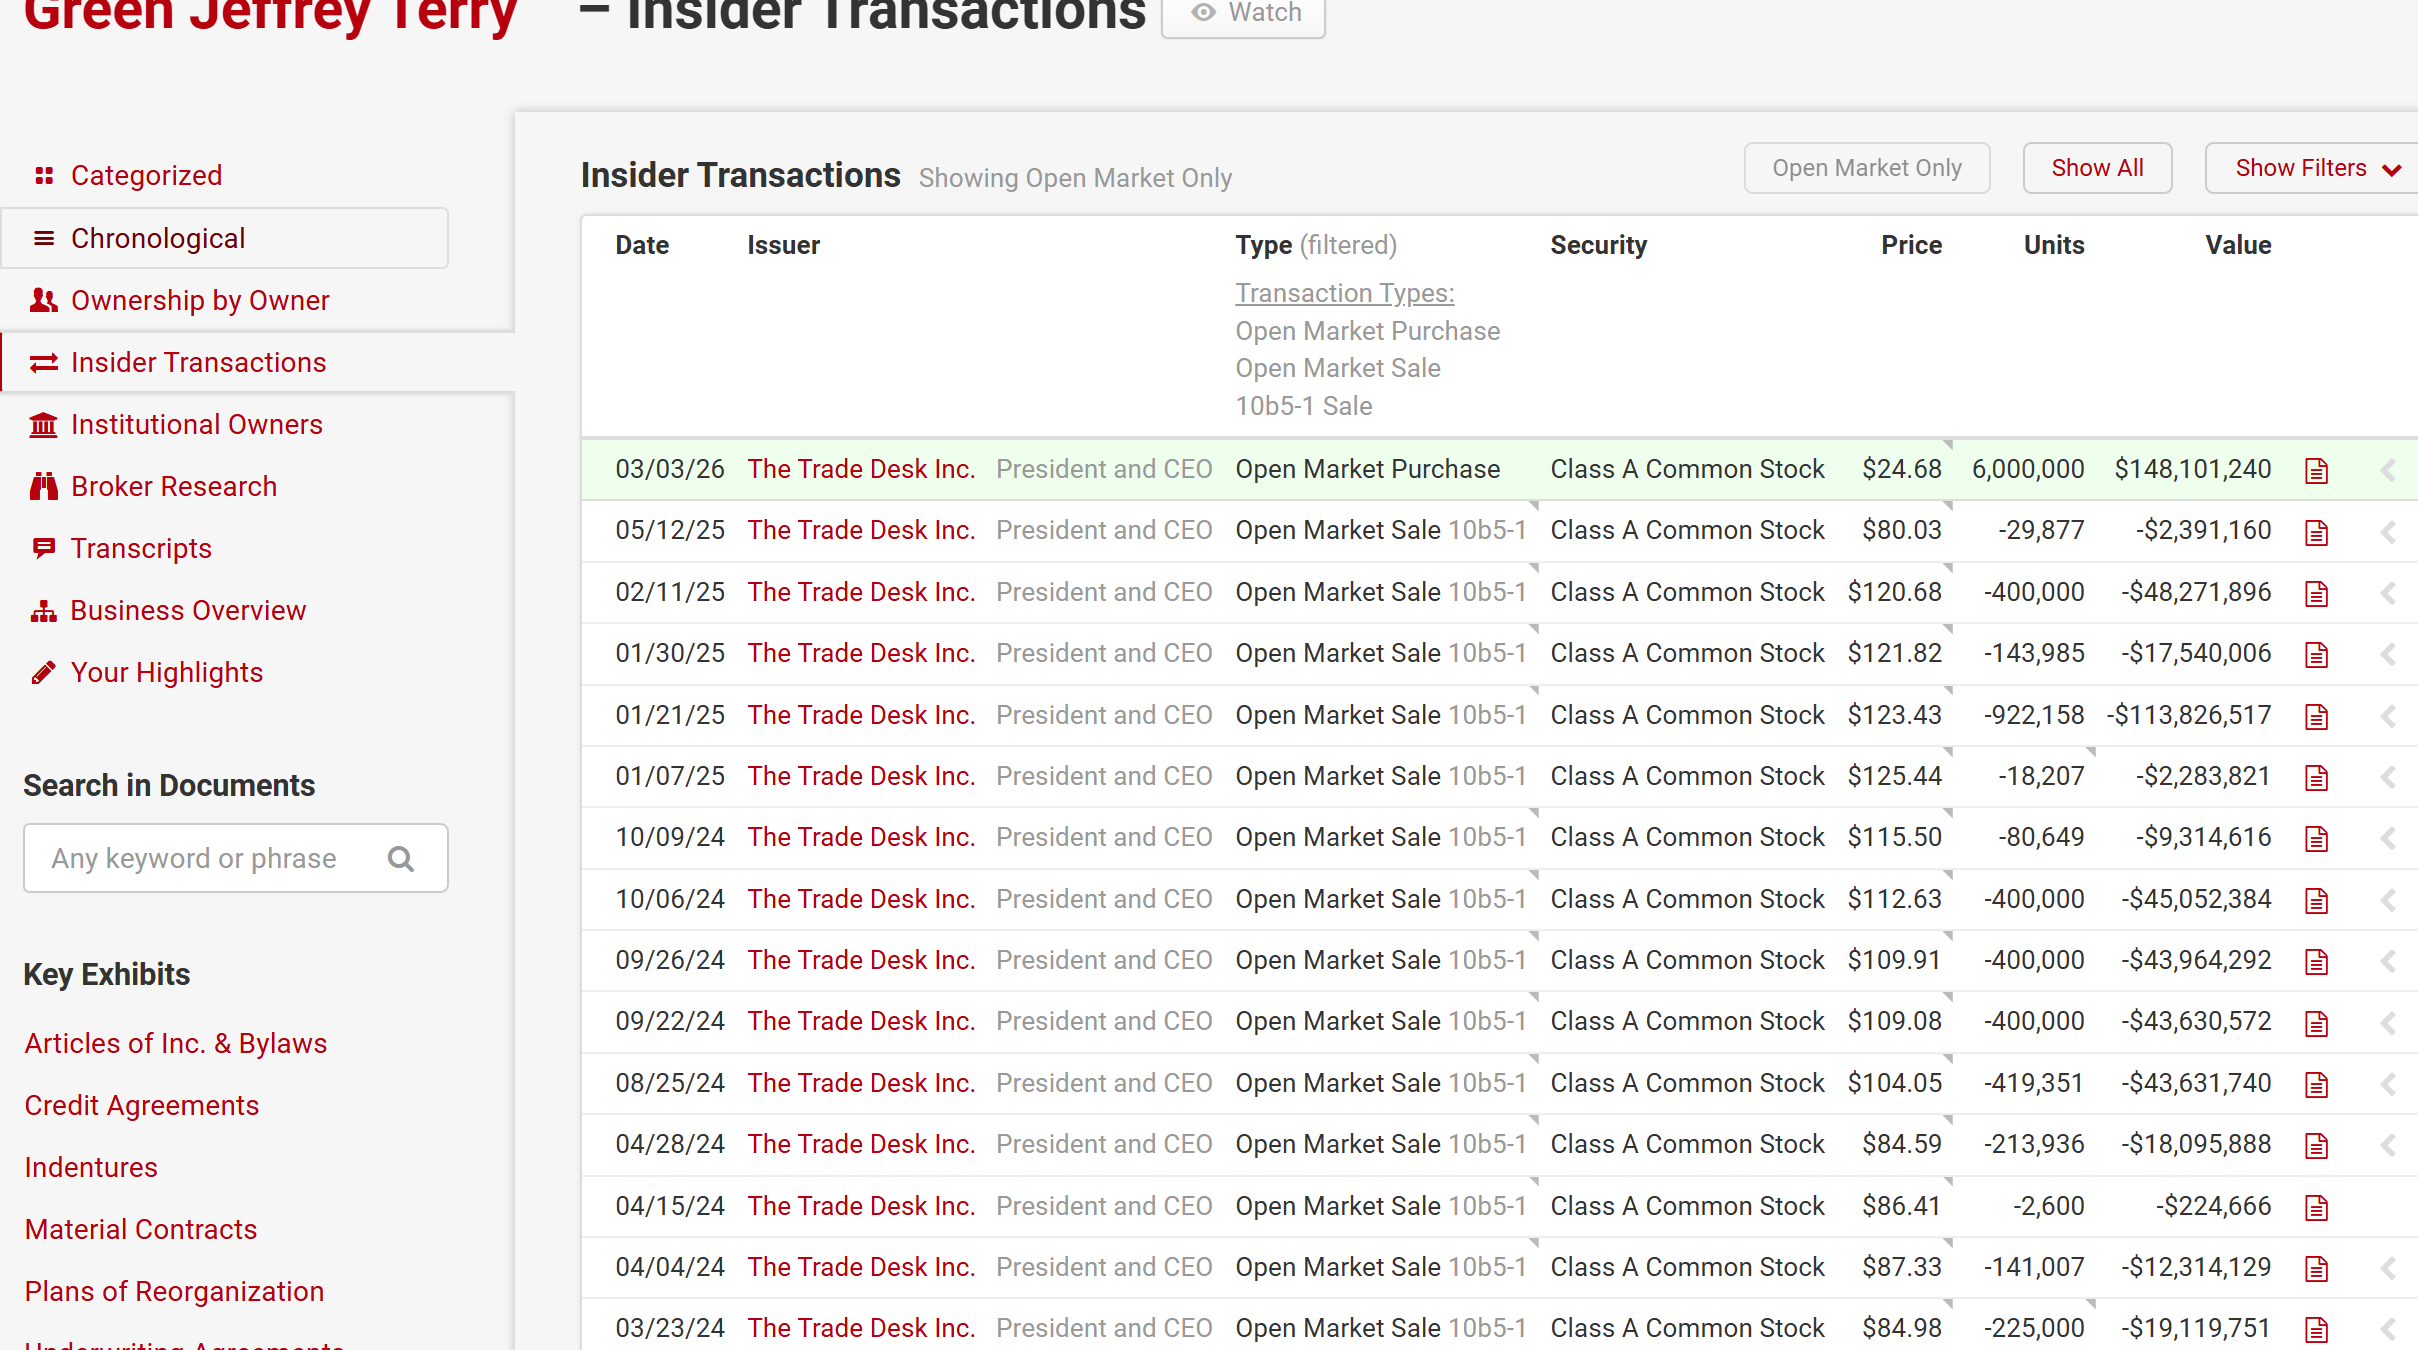
I don’t know the answer. On the one hand, $150m is still a massive check, and the fact that he sold tons of stock in the $80-120/share range and he’s now turning around and buying stock in the $20s suggests he might have a nose for value.
On the other hand, if you (as a CEO) sell >$1B of stock at 4-5x where you just bought, and your board keeps reloading you with options, the $150m buy just doesn’t have quite the same heft to it.
Anyway, it’s a fascinating setup and situation. I’ll admit my priors: I’ve never loved TTD the company or the industry it operates in. Too complex and too hard for me. But, putting my feelings for the business / industry aside, I can’t shake the feeling that TTD just spends lavishly on their compensation and that there’s a whole lot less signal in their pay package than the average company I look at!
On the whole, I’d guess TTD stock performs well from here despite my skepticism; it’s beaten down, and there are plenty of signals that insiders think the selloff is a little too extreme…. but it’s not the type of screaming signal I look for.